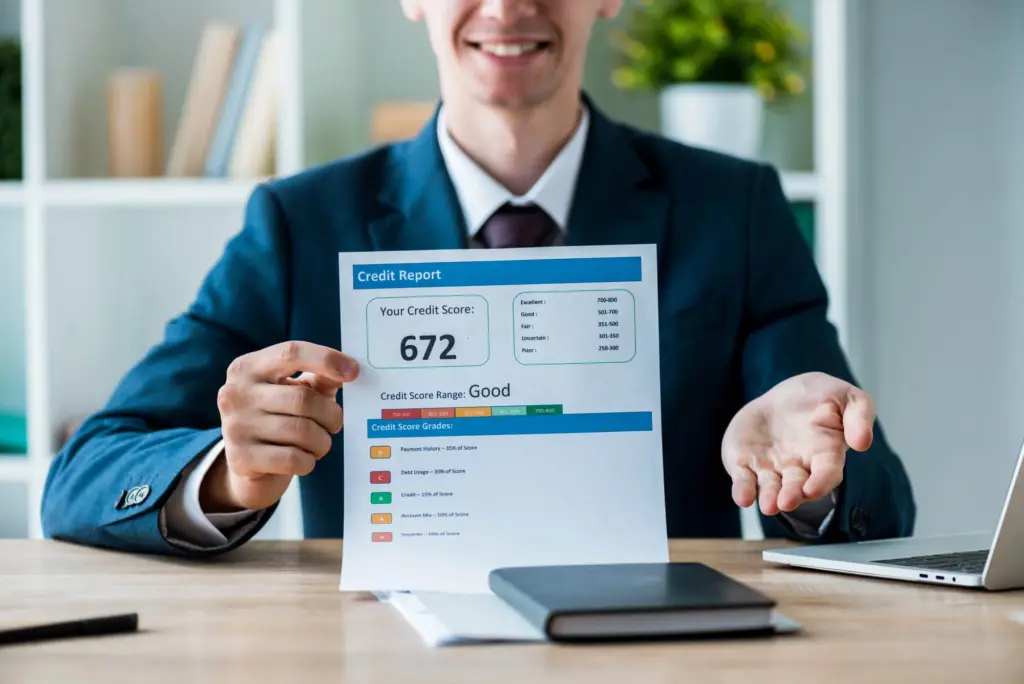
Most people picture a credit report as a private file that only a banker ever opens. The reality is broader. Landlords, employers, insurers, and utility companies may all review parts of it, and most people never learn when it happens. A credit report workshop shows you exactly what those readers see, so nothing on the page catches you off guard. A free credit report analysis with a certified counselor offers a strong first look.
Who Can Pull Your Credit Report
Federal law limits who can request your file. Each requester needs a legally permitted reason, and many need your written consent. Here is how the most common readers use what they find.
Lenders and Creditors
Banks, card issuers, and mortgage companies review your full report when you apply for credit. They study payment history, balances, credit limits, and recent applications. This is the most familiar use of your file, and it shapes the interest rates you are offered. A difference of one or two percentage points on a mortgage or auto loan adds up to thousands of dollars over the life of the loan.
Landlords and Property Managers
Rental applications usually include a screening check with your signed permission. Landlords look for late payments, collection accounts, and heavy debt loads. A short written explanation of a rough patch, such as a job loss or medical bill, can sometimes soften a first impression. Reviewing your report before you apply lets you fix errors first and prepare answers to questions a landlord may raise.
Employers
An employer needs your written permission before pulling a report. They receive a modified version that leaves out your credit score. Roles involving money or sensitive data trigger these checks most often, and federal law requires specific notice steps before an employer acts on what it finds.
Insurers and Utility Companies
In many states, insurers use credit-based information to price auto and home policies, though some states restrict the practice. Utility, internet, and cell phone providers may check your file to decide whether to request a deposit. A clean report can lower costs well beyond loan rates, from insurance premiums to monthly service deposits.
Who Cannot See Your Report
Friends, relatives, neighbors, and coworkers have no right to your file. A spouse needs your permission to view your individual report. Anyone who pulls a report without a permitted reason may violate federal law, and you can ask the bureaus to show you who has accessed your file.
Hard Inquiries Versus Soft Inquiries
Every pull appears in the inquiries section of your report, and the type matters. A hard inquiry follows a credit application, can lower your score slightly, and stays on your report for two years. A soft inquiry, such as an employer check or your own review, leaves your score untouched. Shopping for one loan within a short window usually counts as a single inquiry, so comparing rates carries little risk. The federal consumer protection bureau explains hard versus soft inquiries in plain language.
Take Control of Your Credit Report
You hold more power over your file than most people realize:
- Pull free weekly credit reports from all three bureaus
- Scan the inquiries section for requests you do not recognize
- Place a free credit freeze to block new accounts opened in your name
- Dispute inaccurate information with the bureau and the company that reported it
Companies that reported the error generally must respond to a dispute within 30 days. Unfamiliar inquiries or accounts can signal identity theft, so catching them early protects both your score and your savings. A quick monthly review takes minutes and can prevent months of cleanup. Set a monthly reminder and the habit becomes automatic.
What a Credit Report Workshop Teaches
A credit report workshop turns a confusing document into a plan. Participants learn to read each section, spot errors, and understand how balances and inquiries shape a score. Q&A sessions and real-world examples help the lessons stick, and counselors guide you toward habits that build credit over the long term.
A good workshop answers questions people often hesitate to ask:
- Which accounts help my credit, and which ones hurt it
- Why my score changed after a single application
- How to tell an honest mistake from possible fraud
- Which step to take first when several problems appear at once
Groups can benefit too. DebtHelper offers group financial education seminars for schools, community organizations, and businesses.
When Your Report Shows a Bigger Problem
Rising balances and growing interest often hide behind on-time payments, as these warning signs in your numbers show. A report full of maxed-out cards is useful information, not a verdict. A nonprofit debt management plan may lower interest rates and combine several card payments into one. Counselors review your income, expenses, and balances before recommending anything, so the plan fits your actual budget.
Frequently Asked Questions
Does checking my own credit report lower my score?
No. Reviewing your own report counts as a soft inquiry, so your score stays the same. Checking regularly is one of the simplest ways to catch mistakes early, and free weekly access makes a routine easy to build.
Can my current employer check my credit report?
Only with your written permission, and they see a modified report without your score. Some states also restrict employment credit checks, so rules vary by location.
How long do negative items stay on a credit report?
Most negative items remain for up to seven years. Bankruptcies can stay longer, up to 10 years for some types. Time and steady, on-time payments gradually reduce their weight.
What should I bring to a credit report workshop?
Recent reports from all three bureaus and a list of questions help you get the most from the session. Bring any entries you do not understand so a counselor can explain them.
Join a Credit Report Workshop With DebtHelper
At DebtHelper, we help people of every age make sense of their credit. As an IRS-approved 501(c)(3) nonprofit with certified personal finance counselors, we explain your report in plain language and welcome every question.
If you are ready to see what the world sees, contact our counseling team or call (800) 920-2262. We will gladly walk through your report with you, one section at a time.